

Can French cinema chart its course as the independent theatrical distribution market in the US continues to face polarisation and shifting consumer habits?
France’s film industry is one of the most revered and robust in the world. Some 290 features were produced last year and French films continue to dominate the selections of major global festivals and awards races.
But translating that success into the US distribution market has proven far more difficult. Amid ongoing shifts in the US independent theatrical sector and changes to its own financing models, French cinema has struggled to maintain its foothold in the territory.
Films defined as ‘French’ come in many forms, be it French-language titles, international films made with substantial French backing (see Jafar Panahi’s 2025 Palme d’Or winner It Was Just An Accident), or majority English-language titles from leading French producers (Anatomy Of A Fall) and France-based studios such as Studiocanal, Gaumont, Pathé and EuropaCorp.
In 2025, French-made features grossed a total of $27.8m in the US, up from $20.3m in 2024 and $16.1m in 2023, but all down from pre-Covid tallies ($29.8m in 2019 and $33.3m in 2018) – and far below the $85.7m in 2017, driven largely by a $40m gross for Luc Besson’s Valerian And The City Of A Thousand Planets.
These results mark an even deeper plunge from the box-office peaks of more than a decade ago, when French films often surpassed $100m in the US, hitting $117m in 2015, $140m in 2014 and $208m in 2012.
However, “The figures don’t tell the whole story. We can’t reduce the success of French films in the US to box-office revenue. That era is over,” argues Daniela Elstner, managing director at French film and TV promotion body Unifrance,
There is reason for optimism. French films in 2026 had already surpassed last year’s annual figure by mid-August, with more than $35m. Besson again leads the charge: his latest English-language feature Dracula is the top French title at the US box office in 2026 to date, although its $13m tally is far below the success of his previous English-language blockbusters, which reached a peak in 2014 with Lucy’s $127m haul. (Besson’s The Fifth Element was re-released by Fathom Entertainment in July and managed to make its way to the top films over the first nine months of the year according to Unifrance figures.)
Changing market
The disparity is not limited to Besson-directed tentpoles. “For years, several films would all make more than $1m at the US box office; now we are lucky if a few of them do,” observes Elstner, before adding, “French films are existing in a different way today. The market has shifted. The arthouse cinema crowd for French films has changed.”
Box-office figures are not revealed for French-produced titles snapped up by Netflix for the US, such as Emilia Pérez or Nouvelle Vague, which received limited awards-qualifying theatrical runs before heading swiftly to streaming. Elstner also notes that even if films frequently have short cinema runs, further play at festivals, universities or on streaming platforms can still “nourish an ecosystem in the US of audiences watching French movies – but it is difficult to quantify that”.
In the past decade, around 60-80 French films have been released in US cinemas each year, so quantity is not the issue. However, with shorter windows, nearly obsolete pay-1 deals for foreign-language arthouse films, and the sheer volume of titles in the market today, getting audiences to pay attention is a massive battle.
France’s own financing model has also evolved, with its productions increasingly made in languages other than French and its ubiquitous sales companies selling an expanded catalogue of non-French titles.
“The market is more and more polarised – the middle ground has all but disappeared,” says Fionnuala Jamison, managing director at French sales and production powerhouse mk2 Films. “The bigger US distributors are buying one or two foreign-language films per year, so bidding is competitive as everyone’s going after the same prestige festival standouts. Smaller films are finding homes and prices are stable but, in between, less is happening.”
Amid shifting finance models and distributors boarding earlier in the development stage, smaller distributors are increasingly being shut out from the prestige titles. This year, Neon flew into Cannes having pre-bought six of the films in Competition, increasing its odds of securing its seventh Palme d’Or since 2019 (which it achieved with Fjord) and other top prizes to then catapult its acquisitions into the awards race.
As one French seller says: “Back in the good old days, global French cinema was festival-driven. Today, festival-driven isn’t enough. It needs to be festival-winning.”
When Neon picked up Anatomy Of A Fall in Cannes ahead of the Palme d’Or in 2023, its win propelled the film to awards season success and $5m at the US box office. The company also signed a deal for Oliver Laxe’s Sirât before it won the Cannes jury prize last year and went on to a double Oscar nomination and a $1.75m US gross. IFC Films and Sapan Studios acquired Tran Anh Hung’s The Taste Of Things after its Cannes best director win helped propel a solid box-office run with $2.6m in 2024.
Market polarisation also extends to pricing, with some prestige films able to garner six-figure deals while smaller titles are selling for as low as $5,000-$10,000. There is even talk of some French titles being acquired without a minimum guarantee (MG), although most French sellers and US buyers insist zero-money deals are few and far between.
“Pricing is in the same zone – a bit less than before but it isn’t a dramatic dip, we’re just selling less films,” says Alexandre Moreau, head of sales at Paradise City Sales, whose US deals include Bruno Dumont’s 2024 Berlin jury prize winner The Empire to Kino Lorber, The Divine Sarah Bernhardt to Distrib Films and Judith Godreche’s A Girl’s Story to Zeitgeist Films in association with Kino Lorber.
“Companies like Music Box, Film Movement and Kino Lorber, who were buying so many French films, are now simply buying fewer of them because the market has tightened,” he adds.
Small MGs
Many French sellers tell Screen they have largely written off the US market as a significant contributor to their P&L, knowing many of their films will land with smaller distributors and those MGs will not make their year.
“The US remains an upside, but it’s not a territory we count on when we finance this type of film,” says one French sales agent from a major group that also finances, produces and releases films in France. “It’s always a big gamble – either you lose everything, or you go all in. There is nothing in the middle, so for now, we don’t rely on it in our financing strategy.”
The US box office accounted for 8% of the total revenue for French films outside of France last year, a slight bump on recent years (6.5% in 2024 and 5.2% in 2023), but below its pre-Covid market shares (15.4% in 2017 and 11.4% in 2018).
French films are still being bought in the current climate, and some are finding relative success in North America. Music Box grossed $317,000 with a limited theatrical release for Francois Ozon’s The Stranger this spring. Film Movement has released Dominik Moll’s Case 137 and The Night Of The 12th, while Cohen Media Group, a frequent buyer, recently acquired Stéphane Demoustier’s The Great Arch, Martin Provost’s Bonnard, Pierre & Marthe and Léa Domenach’s The President’s Wife.
Lower expectations
Chasing the dream of a North American release has become a process of lowered expectations for French producers and filmmakers. “French sellers have been realistic in embracing the changes in the US film economy, given how pay-1s have largely retracted from the business and forced them to recast budgets and reduce expectations,” observes Kino Lorber CEO Richard Lorber.
For Nicolas Brigaud-Robert, co-founder of sales and production group Playtime, the challenge for French films today amounts to “a risk management problem”. He explains: “Even when some distributors have an appetite for foreign-language films, the risk to acquire and release them has increased because the DVD market is gone, pay-1 deals are few and far between and don’t always allow for foreign-language films in the deals, and SVoD is complicated to approach.
“The question today is, ‘How do distributors cover their downside?”,’ he continues. “Taking any foreign-language movie today is a highly volatile asset and many distributors are being forced to step away because they don’t know how to mitigate their risk in [the] market.”
Playtime has secured US distribution for several titles in recent years, including Emmanuel Courcol’s 2024 French box-office hit The Marching Band, which Greenwich Entertainment released on August 21; Louis Clichy’s animated Cannes and Annecy prize winner Iron Boy, which was scooped up by Sony Pictures Classics for North America; and Géraldine Nakache’s Think Good, which sold to Cohen Media.
Pay-1 decline
The decline in pay-1 deals has had a particularly devastating impact. With the exception of broad output deals, such as Sony Pictures Classics’ landmark Netflix global pay-1 pact launching in 2027 and Neon’s multi-year output agreement with Disney-owned Hulu, most mid-sized and smaller distributors are struggling to secure similar arrangements – a trend Lorber says is creating a “distortion in the US market”.
“Neon is the indie arthouse distributor that has leaned most heavily into international cinema for awards glory because its financial risk is mitigated,” he says. “Their output deal [with Hulu] has set them on a different playing field.”
Kino Lorber’s own position in the US market is bolstered by the fact it does not rely on pay-1 deals since its titles can go directly from cinemas to its Kino Film Collection streaming platform. It has a library of 2,000 films and 25-30 new releases per year available to its subscribers via distribution partnerships with major streaming platforms such as Prime Video, Roku and Comcast.
“We can project a royalty stream back to filmmakers with subscription streaming revenues along with transactional VoD, educational sales and even home video, all of which gives us more confidence to pursue risk on certain films,” says Lorber.
Even if a mid-level distributor does score a rare pay-1 deal, buyers will issue a single flat license fee without potential for long-term profit.
“The MGs we’re able to offer are slightly lower than in the past, as we no longer have output deals for pay-1 to help alleviate the upfront risk,” says Jon Gerrans, co-founder of Strand Releasing. “Should we be fortunate enough to receive a pay-1 deal after we’ve acquired the film, the license fees are lower than in the past.”
Where are the blockbusters?
As for the larger-scale, French-language crowdpleasers, these have always been tough sells in English-speaking markets and are even harder to export today.
One French seller says: “The US has been a black hole for years when it comes to most French films with bigger budgets and more commercial aspirations.” Lorber cites the discrepancy in these films for US audiences: “Anything with subtitles is immediately relegated to the category of arthouse, and very successful French commercial films rarely earn the critical and festival acclaim that attracts the arthouse crowd.”
Gilles Lellouche’s 2024 local blockbuster Beating Hearts, produced and sold by French powerhouse Studiocanal, is yet to be released in US cinemas despite 5 million admissions in France (for an estimated gross of $36m) and a Cannes Competition premiere. Nor has Cédric Klapisch’s Colours Of Time, a splashy Cannes 2025 premiere and solid local hit for Studiocanal that seemed to contain ingredients that could appeal to a traditional arthouse crowd: a light-hearted, time-hopping narrative centred on French impressionism.
Some US distributors still take a punt. Vertical released Olivier Assayas’ English-language The Wizard Of The Kremlin in May and the film is among the top-performing French titles of the year with $653,000 to date, although the film has a cast topped by Paul Dano, Alicia Vikander and Jude Law. Samuel Goldwyn gave Pathé production The Count Of Monte Cristo a limited US theatrical release in December 2024, when it grossed $530,000 before enjoying a strong run on VoD.
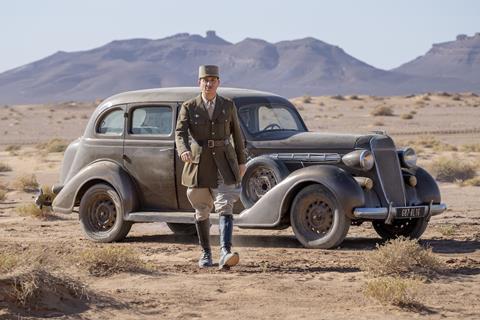
Pathé also managed to strike a US deal for Antonin Baudry’s ambitious, two-part $87m (€75m) historical epic De Gaulle with Samuel Goldwyn after selling to around 20 international markets. “De Gaulle is a film meant to be seen in a movie theatre, and it also has high potential on digital,” says Marie-Laure Montironi, Pathé’s EVP of international sales, who adds that “today, it’s easier to sell a more arty, cinephile film to the US than to sell a film considered to be more commercial in France”.
For those French films that manage to woo a US buyer, the theatrical run has turned into a short sprint rather than the marathons of yesteryear, when a foreign-language film could play for weeks in major urban markets. Fewer cinemas these days play arthouse titles, so the competition for space in the premiere venues is fierce, and films not distributed by bigger companies such as Neon, A24 or Sony Pictures Classics (SPC) navigate a more difficult path. Most distributors need to book these venues at least six months out to secure coveted spots.
To successfully release a French film in the US today, Arianna Bocco, SVP of global distribution at Mubi, suggests: “You need to have an ecosystem in place at every level. You need theatres who can play it, market it and keep it there for several weeks.”
French cinema still benefits from what Bocco calls a “built-in audience [of arthouse enthusiasts] and cinephiles who have watched French cinema over the years”.
Mubi will release exiled Russian filmmaker Andrey Zvyagintsev’s French-produced Minotaur, France’s entry in the best international feature Oscar race, in US theatres on November 20, and Bocco is confident of success: “It won the grand prix in Cannes, it’s from a known director with a fanbase, it’s on an awards pathway, it will appeal to younger audiences and it’s a film that creates conversation.
Niche targeting
Some French sellers say films can thrive in the US market when they target a specific niche audience, whether that be genre, LGBTQ+ or titles that appeal to the country’s Jewish community.
Menemsha, for example, recently acquired Women On Trial starring Charlotte Gainsbourg as famed attorney and activist Gisèle Halimi, and also snapped up Olivier Nakache and Eric Toledano’s Just An Illusion about a French-Jewish family in a Paris suburb in the 1980s. Strand Releasing will release Cannes Critics’ Week prize-winner Flesh And Fuel, about two truck drivers navigating a long-distance romance.
Yet even a clearly defined audience offers no guarantee of theatrical success. Strand Releasing also picked up Hafsia Herzi’s LGBTQ+- themed The Little Sister from mk2 Films after its premiere in the 2025 Cannes Competition, but building awareness for a talented if not well-known director in the US proved to be “an uphill battle”, says Gerrans, who released the title in June.
“We generated around 500,000 geo-targeted impressions on social media, yet the total box office was $80,000,” he says. “People are engaging, they’re clicking, they’re aware of the films, they just aren’t necessarily going to theatres.”
For Bocco, who spent 16 years at IFC Films focused on acquisitions and co-productions before joining Mubi in 2025, the game has not changed – but the players have. “There is less of a homogeneous arthouse cinema monoculture,” she suggests. “The most unique thing about the French film industry is that it is such a hugely integral part of the global film industry. France still produces at least half of all the films coming out of Europe and I have seen a major shift in the market with more English-language titles with French talent and French financing.”
These changes have made the path from Europe to the US much less direct. “Money comes from so many different places, so movies are looking for all different types of deals,” says Dylan Leiner, executive vice president, acquisitions, production and business affairs at Sony Pictures Classics, which released two of the highest-grossing French films of the last two years in Rebecca Zlotowski’s A Private Life ($1.4m) starring Jodie Foster, and Jane Austen Wrecked My Life ($1.9m).
“The traditional way was put up an MG, have a backend split, and off you go. Now there are myriad types of deals to be done, from big upfront deals to backend-driven deals to low-money or even no-money deals.”
While it may seem there are ostensibly less “French” films in the US market, French-produced and French-sold films are ubiquitous. At Cannes this year, 71% of the feature films in selection were repped by French sales agents, as were one third of the titles in the running for 2026’s Oscar for best international feature film. “We are buying more and more from French companies, not necessarily films in the French language but movies funnelled through the French sales agency system,” says Lorber.
Additionally, new players have been arriving on the scene and showing appetites for French and other international fare, among them 1-2 Special, Watermelon Pictures and Willa. 1-2 Special picked up Marine Atlan’s debut feature La Gradiva from mk2 Films for North American distribution after it won the top prize at Cannes Critics’ Week in May. The distributor is targeting younger audiences for the story of French high-school students on a class trip to Pompeii, with a US release scheduled for December.
“We have had a great run with French films and we’re feeling quite bullish about French cinema in general,” insists Leiner. “The traditional audience that has gone to French cinema over the years is now combined with a younger audience discovering both established auteur filmmakers and a new generation of filmmakers.
“People in their 20s and 30s are seeing two or three international movies a week in cinemas and they are joining cinema clubs,” he continues. “They didn’t leave home during Covid so they came out of the pandemic looking to socialise, and movies are a great option.”
As a result, SPC is looking to exploit its strong catalogue of French films further and has also been acquiring movies it did not originally distribute for their initial theatrical runs, such as Jean-Pierre Jeunet’s Amelie, which it re-released in cinemas in 2024.
Even the role of Unifrance has shifted in the US, as the tides change on both sides of the Atlantic Ocean. “We have to diversify the way we promote French cinema and create a desire for it,” says Elstner. In addition to the organisation’s support of distributors and festivals in the US, it is looking to recruit younger audiences to cinemas through multiple programmes while bolstering its social media presence.
“Audiences need to be part of this conversation,” she says. “We can see all over social media that US audiences are showing a desire for French films. As big as the US market is, so are the possibilities.”
No comments yet